
Are Solar Loans Still Worth It at High Interest Rates? A Financial Analysis

Updated: Oct 7

A high interest rate does not automatically make a solar loan a bad financial decision.
But it can change the economics substantially.
The useful question is not:
“Is 8% too high for solar?”
It is:
“After I account for the amount borrowed, interest rate, fees, loan term, total payments and realistic utility savings, does this specific loan still make financial sense?”
There is no universal interest-rate cutoff where solar suddenly stops working financially. Two homeowners can receive the same stated rate and still end up with very different outcomes because their loan principals, terms, fees, electricity costs and expected solar production differ.
This guide shows how to evaluate those numbers without relying on the monthly payment alone.
What a higher solar-loan interest rate actually changes
To isolate the effect of interest, keep everything else constant.
Assume:
$21,000 loan
15-year term
fixed monthly payments
no additional financing fees
no down payment
no early payoff
Here is what happens as the fixed interest rate changes:
Fixed interest rate | Monthly payment | Total payments | Total interest |
5% | $166.07 | $29,892.00 | $8,892.00 |
7% | $188.75 | $33,975.71 | $12,975.71 |
8% | $200.69 | $36,123.65 | $15,123.65 |
9% | $213.00 | $38,339.28 | $17,339.28 |
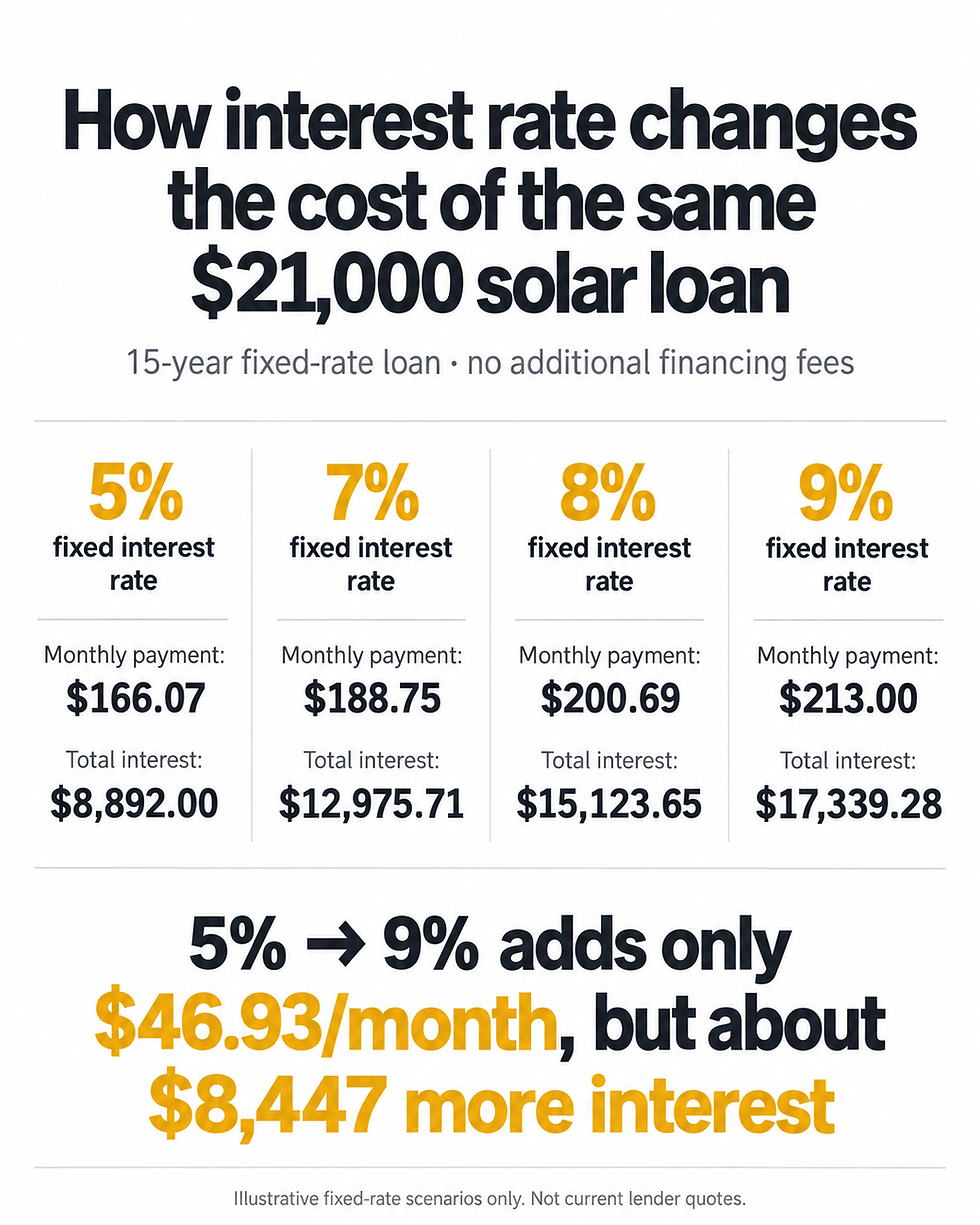
Moving the rate from 5% to 9% increases the payment by about $46.93 per month.
The bigger difference appears over time: total interest rises by about $8,447.28.
That is why a rate that changes a payment by only a few dozen dollars can still materially change the long-term economics.
A $21,000 loan at 8% over 15 years does not produce only about $8,640 in interest. Under standard monthly amortization and the assumptions above, interest is about $15,123.65.
The equipment has not changed. The borrowing cost has.
Interest rate is not the same as total financing cost
The stated interest rate matters, but it is not the only number to inspect.
The Consumer Financial Protection Bureau defines an interest rate as the cost charged for borrowing the principal. APR is broader: it reflects the interest rate and additional fees charged with the loan.
For a solar loan, compare at least these four numbers:
Cash price → Amount financed → APR → Loan term
Why the cash price?
The CFPB has found solar-specific loans where fees or markups increased the loan principal by 30% or more above the cash price. Some of these costs can be incorporated into the principal rather than presented separately as borrowing costs.
Consider two hypothetical financing offers:
Loan A has the lower stated rate but finances a substantially higher principal.
Loan B has the higher rate but starts with a lower principal.
The lower stated rate does not automatically make Loan A cheaper.
Ask:
What is the cash price of this exact system?
What amount am I actually financing?
What is the APR?
What will I pay if I make every scheduled payment?
For the broader choice among cash, loans and third-party ownership, use our solar financing guide.
For the mechanics behind solar dealer fees, use our solar dealer-fee guide.
A lower monthly payment can still cost more overall

The monthly payment is one of the easiest financing numbers to compare.
It is also one of the easiest to overvalue.
We saw this in a real IntegrateSun proposal.
The same 16.72 kW equipment configuration — 38 SEG Solar 440W panels with 38 Enphase IQ8HC microinverters — had one 30-year option at $264 per month and one 20-year option at $331 per month after the first six months. The proposal listed total payments of $94,865.47 and $79,168.72, respectively.
The lower monthly payment came with $15,696.75 more in listed total payments.
These were not identical loans. Their interest rates, starting principals and payment schedules also differed.
That is precisely the lesson:
The monthly payment alone did not reveal the total financing cost.
Use our solar quote-comparison guide for the complete real-proposal breakdown.
Check the prepayment and payment-reset terms
Paying a solar loan off early may reduce the interest you ultimately pay.
But do not assume every loan handles prepayment in the same way.
The CFPB has documented solar-specific loans structured around an expected principal prepayment. In some of those loans, the required monthly payment increased if the borrower did not make the expected reduction by a specified date.
That CFPB report predates the current federal residential tax-credit rules, so it should not be read as proof that a current lender uses the same structure.
The lesson is simpler:
Read your actual payment schedule.
Before signing, ask:
Is there a prepayment penalty?
Is any large principal payment expected by a certain date?
Does the loan re-amortize?
Can the required payment increase later?
What happens if I make extra principal payments?
What happens if I pay the loan off entirely?
“No prepayment penalty” and “your payment can never change” are not the same statement.
Federal tax-credit status
Older solar-loan calculations often assumed the homeowner would receive a federal residential solar tax credit and use that money to reduce the loan principal.
That assumption should not appear in a current financing analysis.
The IRS states that the Residential Clean Energy Credit under Section 25D is not allowed for expenditures made after December 31, 2025. For Section 25D, the expenditure is generally treated as made when the original installation is completed. Completing installation after December 31, 2025 does not preserve the credit merely because the homeowner paid earlier.
So the old idea that the homeowner credit simply stepped down to 26% in 2026 is no longer correct.
State, utility and other programs still vary, so keep those separate from the loan calculation until eligibility has been verified.
Use our solar incentives guide for current program-specific information.
How do you know if a high-rate solar loan still makes sense?

Do not start with a generic rule such as:
“Solar works below 9%.”
There is no defensible universal cutoff.
Instead, gather the numbers for the actual project.
Step 1: Establish the system's cash economics
Know:
cash price
expected first-year solar generation
electricity usage used in the design
utility tariff assumptions
expected remaining utility charges after solar
Financing cannot correct an unrealistic system price or production assumption; it only changes how the project is paid for.
For more detail on the underlying system price and payback assumptions, use our solar cost guide.
Step 2: Establish the borrowing economics
Know:
amount financed
stated interest rate
APR
loan term
monthly payment
total of scheduled payments
financing or origination costs
payment-reset conditions
prepayment terms
Do not substitute the monthly payment for this list.
Step 3: Compare the same time period
This is easy to get wrong.
If you are evaluating a 15-year loan, compare the relevant solar and utility costs across the same 15-year period.
Do not compare 15 years of loan payments against 25 or 30 years of estimated utility spending and call the difference “savings.”
For a chosen time horizon, think about the comparison this way:
Without solar:Expected utility spending over that period.
With financed solar:Loan payments during the period + expected remaining utility bills + other known costs.
Any future utility-rate increases are assumptions, not guarantees. Run conservative scenarios rather than choosing an aggressive escalation rate solely to make the solar option appear better.
Step 4: Test the assumptions, not just the result
A proposal can show attractive lifetime savings while relying on assumptions that deserve scrutiny.
Check:
production estimate
degradation assumption
utility-rate assumptions
export-credit or net-metering treatment
remaining fixed utility charges
expected ownership period
maintenance or replacement assumptions that materially affect the comparison
The CFPB warns that there is no guarantee a solar loan will pay for itself, and actual financial benefits can vary with system performance, geography, utility structure and other factors.
A savings projection is only as credible as the assumptions beneath it.
When can a high-rate solar loan fail the financial test?
The interest rate itself is only one warning sign.
The bigger problems often appear when several factors stack together.
A high-rate loan deserves extra scrutiny when:
the financed amount is materially higher than the system's cash price and the difference is not clearly explained;
the term is stretched mainly to make an expensive loan look affordable each month;
total financing cost absorbs most of the expected electricity savings;
the proposal assumes unusually aggressive utility-rate increases;
solar production assumptions appear optimistic;
the payment can rise later and that change is not reflected in the homeowner's budget;
the expected ownership period is much shorter than the time required for the economics to work;
fees, prepayment conditions or other loan terms are unclear.
None of these automatically proves the project is bad.
They tell you where to investigate before signing.
What if the solar-loan math does not work?
Do not force a loan structure simply because you want solar.
You may have other ways to structure the project, including paying cash, comparing another lender, using a shorter or differently priced loan, considering an appropriate home-equity product, or reviewing third-party ownership options where available.
Each alternative has different ownership, tax, collateral and contract implications.
That broader decision belongs in our solar financing guide.
The purpose of this page is narrower:
determine if the solar loan in front of you makes financial sense.
Questions to ask before signing a high-interest solar loan
Before agreeing to the loan, you should be able to answer these questions:
What is the cash price of this exact system?
What amount am I financing?
Why is the amount financed different from the cash price, if it is?
What is the stated interest rate?
What is the APR?
How long is the loan term?
What is the required monthly payment?
Can that payment change?
What are the total scheduled payments?
Are any dealer, origination or other financing costs embedded in the principal?
Is a large principal prepayment expected?
What happens if I do not make it?
Is there a penalty or other condition if I pay the loan off early?
What production and utility-rate assumptions support the projected savings?
Over the period I expect to own the home, how does financed solar compare with continuing to buy electricity without solar?
If those answers are clear, you can evaluate the economics.
If they are not, the interest rate is not yet the biggest problem.
So, are solar loans still worth it at high interest rates?
Sometimes.
But “solar is worth it” and “this solar loan is worth it” are two different conclusions.
A higher borrowing rate increases the hurdle the project has to clear. A longer loan term can make the monthly payment easier while increasing total interest. Financing fees can raise the principal before interest is calculated. And projected electricity savings depend on assumptions that need to hold up in the real world.
That is why the best test is not a national rate threshold.
It is the math for your actual home:
cash price + amount financed + APR + term + total payments + realistic utility economics.
If you are reviewing a solar proposal, IntegrateSun can help you put those numbers side by side before you make the financing decision.


